
Prestige Park Street EMI Calculator
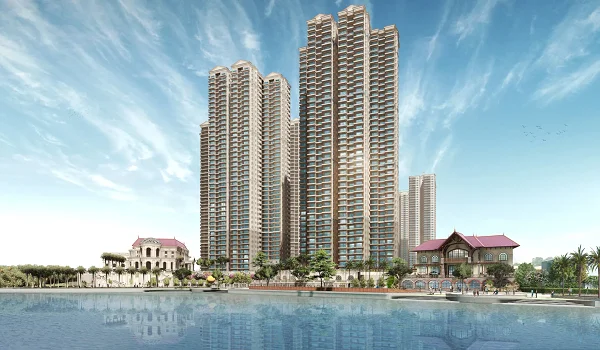
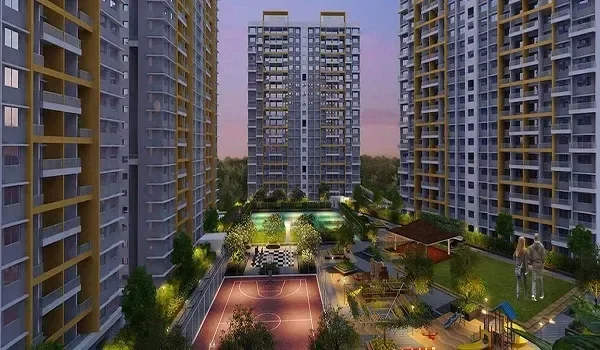
The Prestige Park Street EMI calculator shows that buying a base 3 BHK home here costs around ₹2,46,056 each month. This estimate starts with a home price of ₹4.00 Crores, an 80% bank loan of ₹3.20 Crores, a loan period of 30 years, and an 8.50% interest rate. The project covers 3.48 acres on Velachery 100 Feet Road in Chennai (PIN 600042). It has 252 luxury flats spread across 4 towers, each rising 18 floors high. Home sizes run from 2,280 sq ft for a 3 BHK up to 4,288 sq ft for a large 4 BHK with a family room. For the largest flat, the monthly EMI climbs to ₹4,61,355 under the same loan terms.
Buyers can use this simple tool to plan their budget with peace of mind. The payments link straight to the builder’s 10-step payment plan, so you only pay as work gets done, from digging the ground to getting your keys by 31 October 2030.
Prestige Park Street EMI Calculator Formula and Calculation Methodology
The Prestige Park Street EMI calculator uses the standard reducing-balance method to work out the monthly EMI. It considers the loan amount, monthly interest rate, and loan tenure to calculate the payment for each month.
EMI = [P × R × (1 + R)^N] / [(1 + R)^N - 1]
- P (Principal Loan Amount): The net loan sanctioned by retail banks (such as SBI, HDFC, ICICI, or Axis Bank), which typically covers 75% to 80% of the flat's registered agreement value.
- R (Monthly Interest Rate): The yearly loan interest rate divided by 12 and converted into a decimal fraction ($8.50\% \div 12 \div 100 = 0.007083$).
- N (Tenure in Months): The agreed repayment period counted in monthly installments (for instance, a 20-year term equals 240 months).
Because the loan runs on a reducing balance basis, your interest liability gets smaller after every monthly payment. In the first few years, interest makes up roughly 65% to 70% of each installment. As the unpaid loan balance drops over time, a larger share of your money goes straight toward paying off the actual property.
Prestige Park Street Unit Configurations, Base Prices, and Total Cost Outlays
Early booking prices at Prestige Park Street start around ₹17,500 for every square foot before the full launch on 05 October 2026. The table below lists the flat sizes, base prices from the builder, and the total cost you can expect to pay with all key fees included.
| Loan Tenure | Monthly EMI Outflow | Total Interest Payable | Total Repayment (Principal + Interest) |
|---|---|---|---|
| 15 Years (180 months) | ₹3,15,127 | ₹2,47,22,860 | ₹5,67,22,860 |
| 20 Years (240 months) | ₹2,77,651 | ₹3,46,36,240 | ₹6,66,36,240 |
| 30 Years (360 months) | ₹2,46,056 | ₹5,65,80,160 | ₹8,85,80,160 |
Configuration-Wise Monthly EMI Schedules Across 15-, 20-, and 30-Year Tenures
The following tables show monthly installments assuming an 80% loan-to-value (LTV) share and a benchmark floating interest rate of 8.50% per year.
1. 3 BHK Luxury Apartment (2,280 sq ft)
- Base Value: ₹4,00,00,000
- 20% Down Payment: ₹80,00,000
- Loan Amount (80%): ₹3,20,00,000
| Loan Tenure | Monthly EMI Outflow | Total Interest Payable | Total Repayment (Principal + Interest) |
|---|---|---|---|
| 15 Years (180 months) | ₹4,16,755 | ₹3,26,95,900 | ₹7,50,15,900 |
| 20 Years (240 months) | ₹3,67,194 | ₹4,58,06,560 | ₹8,81,26,560 |
| 30 Years (360 months) | ₹3,25,409 | ₹7,48,27,240 | ₹11,71,47,240 |
2. 4 BHK Luxury Apartment (3,024 sq ft)
- Base Value: ₹5,29,00,000
- 20% Down Payment: ₹1,05,80,000
- Loan Amount (80%): ₹4,23,20,000
| Loan Tenure | Monthly EMI Outflow | Total Interest Payable | Total Repayment (Principal + Interest) |
|---|---|---|---|
| 15 Years (180 months) | ₹5,23,110 | ₹4,10,39,800 | ₹9,41,59,800 |
| 20 Years (240 months) | ₹4,60,901 | ₹5,74,96,240 | ₹11,06,16,240 |
| 30 Years (360 months) | ₹4,08,453 | ₹9,39,23,080 | ₹14,70,43,080 |
3. 4.5 BHK + Study Residence (3,797 sq ft)
- Base Value: ₹6,64,00,000
- 20% Down Payment: ₹1,32,80,000
- Loan Amount (80%): ₹5,31,20,000
| Loan Tenure | Monthly EMI Outflow | Total Interest Payable | Total Repayment (Principal + Interest) |
|---|---|---|---|
| 15 Years (180 months) | ₹5,90,863 | ₹4,63,55,340 | ₹10,63,55,340 |
| 20 Years (240 months) | ₹5,20,596 | ₹6,49,43,040 | ₹12,49,43,040 |
| 30 Years (360 months) | ₹4,61,355 | ₹10,60,87,800 | ₹16,60,87,800 |
4. 4 BHK + Family Room (4,288 sq ft)
- Base Value: ₹7,50,00,000
- 20% Down Payment: ₹1,50,00,000
- Loan Amount (80%): ₹6,00,00,000
| Loan Tenure | Monthly EMI Outflow | Total Interest Payable | Total Repayment (Principal + Interest) |
|---|---|---|---|
| 15 Years (180 months) | ₹5,90,863 | ₹4,63,55,340 | ₹10,63,55,340 |
| 20 Years (240 months) | ₹5,20,596 | ₹6,49,43,040 | ₹12,49,43,040 |
| 30 Years (360 months) | ₹4,61,355 | ₹10,60,87,800 | ₹16,60,87,800 |
Construction-Linked Payment (CLP) Milestones vs. Pre-EMI Loan Tranches
Paying more cash upfront cuts down how much you need to borrow. It also saves you a lot of interest money down the road.
The table below shows how different down payments change your monthly costs for a 3 BHK flat (priced at ₹4.00 Crores) on a 20-year loan at an 8.50% interest rate.
| Milestone | Construction Progress on Site | Payment Due (%) | Disbursed Amount (3 BHK at ₹4 Cr) | Cumulative Loan Disbursal |
|---|---|---|---|---|
| Milestone 1 | Booking Amount / Unit Block | 10% | ₹40,00,000 | ₹40,00,000 |
| Milestone 2 | Signing of Agreement of Sale | 10% | ₹40,00,000 | ₹80,00,000 |
| Milestone 3 | Completion of Site Excavation | 10% | ₹40,00,000 | ₹1,20,00,000 |
| Milestone 4 | Core Plinth Level Completion | 10% | ₹40,00,000 | ₹1,60,00,000 |
| Milestone 5 | Two Basement Slabs (2B) | 10% | ₹40,00,000 | ₹2,00,00,000 |
| Milestone 6 | Ground Floor Structural Slab | 10% | ₹40,00,000 | ₹2,40,00,000 |
| Milestone 7 | Superstructure (up to 18th Floor) | 10% | ₹40,00,000 | ₹2,80,00,000 |
| Milestone 8 | Internal Flat Flooring Work | 10% | ₹40,00,000 | ₹3,20,00,000 |
| Milestone 9 | Internal Plumbing & Finishing | 10% | ₹40,00,000 | ₹3,60,00,000 |
| Milestone 10 | Occupancy Certificate & Handover | 10% | ₹40,00,000 | ₹4,00,00,000 |
- Pre-EMI Interest Structure: In Pre-EMI mode, you only pay monthly interest on the money released to the builder so far. For example, once the ground floor slab is finished (Milestone 6: ₹2.40 Crores total disbursed), the monthly Pre-EMI at 8.50% interest comes to ₹1,70,000. Your main loan balance stays the same until final handover.
- Full EMI Structure: Choosing full monthly installments from the very first payment begins reducing the borrowed principal right away. While this requires higher monthly spending during construction, it cuts total interest costs by 18% to 22% over the full life of the loan.
Impact of Down Payment Percentages on Monthly EMI Outflow
A higher down payment means a lower loan amount. This can reduce the total interest you pay over the loan period. The table below compares different down payments for a ₹4 crore 3 BHK with a 20-year loan at 8.50% interest.Down Payment (%) Equity Paid (₹)
| Down Payment (%) | Equity Paid (₹) | Loan Amount (₹) | Monthly EMI (₹) | Total Interest Paid (₹) | Cumulative Savings (₹) |
|---|---|---|---|---|---|
| 10% Down Payment | ₹40,00,000 | ₹3,60,00,000 | ₹3,12,357 | ₹3,89,65,770 | Baseline |
| 15% Down Payment | ₹60,00,000 | ₹3,40,00,000 | ₹2,95,004 | ₹3,68,00,960 | ₹21,64,810 |
| 20% Down Payment | ₹80,00,000 | ₹3,20,00,000 | ₹2,77,651 | ₹3,46,36,240 | ₹43,29,530 |
| 25% Down Payment | ₹1,00,00,000 | ₹3,00,00,000 | ₹2,60,298 | ₹3,24,71,520 | ₹64,94,250 |
| 30% Down Payment | ₹1,20,00,000 | ₹2,80,00,000 | ₹2,42,945 | ₹3,03,06,800 | ₹86,58,970 |
- Lower Monthly Payments: Moving your initial down payment from 10% to 30% lowers your required monthly installment by ₹69,412.
- Interest Savings: Putting down an extra ₹80 Lakhs upfront saves you ₹86.58 Lakhs in total interest over 20 years.
Bank Eligibility Criteria and Income Thresholds for Prestige Park Street Loans
Banks check your monthly income and debt habits before giving final approval for a high-value home loan.
- Fixed Obligation to Income Ratio (FOIR): Most major banks require that all your monthly loan payments, including this new mortgage, take up no more than 55% to 65% of your take-home pay. For a monthly payment of ₹2,77,651 on a 3 BHK over 20 years, your household needs a proven net monthly income between ₹4.50 Lakhs and ₹5.00 Lakhs.
- Credit Score Standards: A credit score above 750 (CIBIL or Experian) gives you access to lower home loan interest rates starting around 8.35% to 8.50%. Scores below 700 can add a risk fee of 0.25% to 0.50% to your interest rate.
- Applying with a Co-Borrower: Adding a working spouse or family member as a co-applicant lets you combine incomes to meet bank eligibility rules. This setup also lets both co-owners claim home loan tax deductions under Section 24(b) and Section 80C.
Ancillary Costs and Statutory Charges Excluded from Loan Calculations
Home loans only cover the base cost written in the builder agreement. You must arrange your own funds to pay government taxes, connection fees, and society deposits.
- Tamil Nadu Stamp Duty and Registration Charges: The state government charges a 5% stamp duty plus a 1% registration fee when you sign the sale deed, which comes to around ₹24 Lakhs on a ₹4.00 Crore 3 BHK unit.
- Goods and Services Tax (GST): Ongoing property construction in Tamil Nadu carries a flat 5% GST without input tax credit, adding another ₹20 Lakhs to the purchase cost.
- Advance Maintenance Corpus: Running maintenance across the 3.48-acre property is estimated between ₹4 and ₹6 per sq ft each month. For a 2,280 sq ft unit, an advance 1 to 2-year maintenance fee of roughly ₹1,10,000 to ₹2,20,000 is due before possession on 31 October 2030.
- Floor Rise and Location Charges: Flats on upper floors or units facing the central garden and clubhouse carry extra developer charges between ₹150 and ₹450 per sq ft.
FAQs
The lowest EMI is around ₹2,46,056 for a 2,280 sq. ft. 3 BHK priced at ₹4 crore. This assumes an 80% loan of ₹3.20 crore for 30 years at an 8.50% interest rate.
Yes, this may be possible with some banks. Buyers can switch to full EMI during construction, depending on the bank's terms. This can help reduce the loan balance sooner.
SBI, HDFC Bank, ICICI Bank, and Axis Bank may offer home loans for the project, subject to their approval and loan rules.
The EOI amount is ₹10 lakh for a 3 BHK, ₹15 lakh for a 4 BHK, and ₹20 lakh for a 4.5 BHK. The final payment terms may vary based on the sale agreement.
No. The EMI covers the loan principal and interest. Stamp duty, registration charges, GST, and maintenance fees are paid separately. Maintenance may be around ₹4 to ₹6 per sq. ft.